Small businesses often build their employee benefits packages around medical coverage first. As the workforce grows, employers may also consider dental, vision, life, disability, and other forms of coverage that address different employee needs. Voluntary benefits can add another layer of choice by allowing eligible employees to consider additional insurance options offered through the workplace.
For Florida employers, the challenge is deciding which options serve a clear purpose. A longer list of benefits does not automatically create a stronger program. Employers should understand what each product is designed to address, how it fits with existing coverage, how employees will enroll, and how clearly the benefit can be explained.
ProCare Consulting includes voluntary benefits among its small-group employee-benefit services, alongside health plans, group life, AD&D, dental, vision, and short- and long-term disability coverage.
This guide explains how voluntary employee benefits for small businesses can fit into a broader benefits strategy, which types employers may encounter, what to review before adding them, and how different workforces may approach these options.
Where Do Voluntary Benefits Fit Into a Small Business Benefits Package?
Voluntary benefits generally sit alongside the employer’s core benefits rather than taking their place. Their role is to give eligible employees access to additional forms of coverage that address specific financial or insurance needs.
For employers, the most useful approach is to consider these products in the context of the entire employee benefits package. Medical, dental, vision, life, disability, and voluntary coverage all serve different purposes.
Voluntary Benefits Complement Core Employee Coverage
Medical insurance is designed around eligible healthcare services and expenses under the applicable health plan. Voluntary products may address different circumstances, depending on the specific policy.
For example, ProCare’s broader ancillary offerings include products such as accident plans, critical illness coverage, hospital indemnity, and life insurance. When similar products are offered through an employer’s benefits program, employees should understand that each policy has its own terms, eligibility requirements, limitations, and benefit structure.
The objective is to build a coordinated benefits package rather than treating each product as an isolated add-on.
Employees May Choose Coverage Based on Their Own Needs
Voluntary benefits can give employees additional choices within the benefits program.
One employee may be interested in supplemental life coverage, while another may place more value on an accident, critical illness, or hospital indemnity option. Employees may also decide that the core benefits already available are sufficient for their circumstances.
Employers should provide accurate information about the options without assuming that every employee needs the same voluntary coverage.
Voluntary Benefits Should Have a Defined Purpose
Before adding another product, employers should understand why it belongs in the benefits package.
A useful review can begin with simple questions. What does the policy provide? Which risk is it designed to address? How does it differ from benefits the company already offers? Will employees be able to understand the distinction?
This approach helps prevent a benefits program from becoming unnecessarily complicated.
What Types of Voluntary Benefits Can Small Employers Consider?
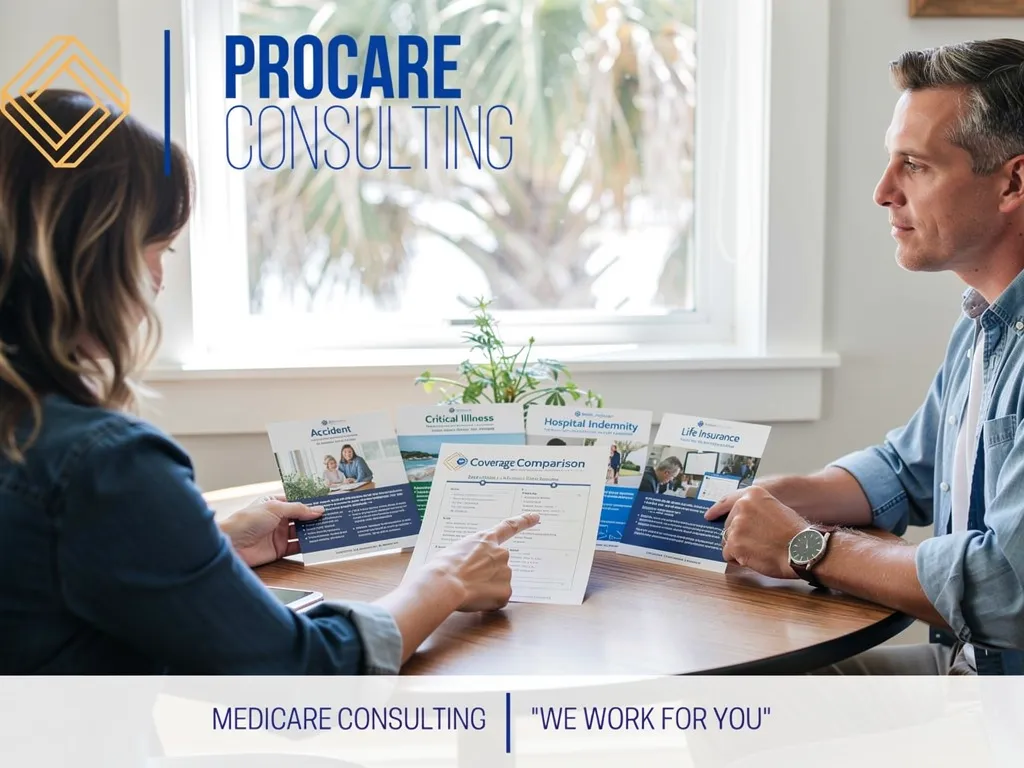
Available voluntary products vary by employer, carrier, and program. Employers should confirm actual availability and policy terms before describing any coverage to employees.
Several common categories may appear in a small-business benefits discussion.
Accident Insurance
Accident insurance may provide policy-defined benefits following qualifying accidental injuries or events.
The exact covered circumstances, benefit amounts, exclusions, and claim requirements depend on the applicable policy. Employers should therefore avoid broad statements suggesting that every accident will result in a benefit.
Accident insurance should also be explained separately from medical insurance and workers’ compensation. Each type of coverage serves a different purpose and operates under its own terms.
Critical Illness Insurance
Critical illness insurance may provide a defined benefit when a covered individual experiences a qualifying diagnosis or event listed in the policy.
Covered conditions and benefit structures vary. Employees should review the actual policy rather than assuming every serious illness is included.
For employers, the key communication point is that critical illness coverage is a separate form of insurance designed around policy-defined events. It should not be presented as a replacement for comprehensive medical coverage.
Hospital Indemnity Insurance
Hospital indemnity coverage generally provides benefits according to policy terms when qualifying hospital-related events occur.
The payment structure may differ from a traditional health plan because the policy is designed around its own defined benefits rather than paying medical claims in the same way as major medical insurance.
ProCare lists hospital indemnity among its ancillary insurance offerings. Employers offering a similar product through a voluntary benefits program should explain that distinction clearly during enrollment.
Supplemental Life Insurance
Some employee benefits programs may allow workers to elect additional life insurance beyond any employer-provided basic group life coverage.
Availability, benefit amounts, dependent options, evidence requirements, portability provisions, and other terms can vary by policy.
Because life insurance serves a different purpose from accident or health coverage, employees should receive separate information explaining the applicable option.
Other Voluntary Products
Other voluntary products may be available depending on the employer and insurance carrier.
Employers should resist the temptation to offer every available product simply because it exists. Each additional option creates another benefit employees must understand and another administrative item the business may need to manage.
The stronger approach is to select benefits that fit the workforce and complement the existing program.
How Are Voluntary Benefits Different From Core Employer Benefits?
Benefits offered through the workplace can have different funding arrangements, election procedures, and purposes. Employees should understand those differences before making enrollment decisions.
Clear communication is especially important when core and voluntary benefits are presented together.
Employer-Paid and Employee-Paid Benefits Are Not the Same
Some employee benefits may be fully employer-paid. Others may involve employee contributions, and voluntary coverage may often require an employee election and employee-paid premiums.
However, employers should not describe all voluntary benefits as automatically 100% employee-paid because arrangements can differ.
Employees should be told clearly who pays for each benefit and how any applicable contribution or payroll deduction works.
Employees Usually Make Their Own Elections
Voluntary benefits generally involve an employee decision.
When an employer makes several voluntary options available, employees should have an opportunity to review what each product does, understand applicable enrollment requirements, and decide whether they want to participate.
Employers should avoid pressuring employees toward a particular product.
Each Product Has Separate Policy Terms
Accident, critical illness, hospital indemnity, life insurance, and other products are separate forms of coverage.
Even two policies in the same category can contain different definitions, exclusions, limitations, benefit amounts, or enrollment rules.
Employee-friendly explanations are useful, but the applicable policy should remain the source of truth for specific coverage details.
Voluntary Coverage Does Not Replace Medical Insurance
This distinction should be made clear during enrollment.
Supplemental or voluntary insurance products are designed to provide their own defined benefits. They should not be described as substitutes for comprehensive group medical insurance.
ProCare similarly presents supplemental products separately from its small-group health insurance offerings.
What Should a Small Business Review Before Adding Voluntary Benefits?
Adding voluntary benefits should begin with a review of the existing program rather than a product catalog. Employers can use the current benefits package, workforce structure, employee questions, and administrative capabilities to decide whether additional options deserve consideration.
Review the Existing Benefits Package First
Start by documenting what employees already have access to.
A small business may offer medical, dental, vision, life, disability, AD&D, or other benefits. ProCare’s small-group offering includes these categories alongside voluntary benefits.
Understanding the existing program makes it easier to see where an additional product adds something distinct and where it may duplicate another benefit.
Identify Gaps in the Current Benefits Strategy
Employers can consider whether the current benefits package leaves areas employees may want additional options to address.
For example, the business may already provide medical and dental insurance but have limited additional financial-protection options. Another employer may already offer life and disability coverage, reducing the need for certain overlapping products.
There is no universal set of voluntary benefits that every small business should offer.
Consider Workforce Composition
Workforce characteristics can influence which benefits deserve attention.
A company with field employees may approach benefits differently from a professional-services business where most employees work at desks. A business with a combination of younger employees, workers with dependents, managers, technicians, and administrative employees may have varied priorities.
Employers can evaluate broad workforce needs and preferences without asking employees to disclose unnecessary medical information.
Look for Unnecessary Benefit Overlap
Several products may appear to address similar financial risks even though their policy terms differ.
Employers should review where coverage overlaps and where it remains distinct. Disability insurance, accident insurance, critical illness coverage, hospital indemnity, life insurance, and medical coverage should each have an understandable place within the program.
If the employer cannot clearly explain why two products are different, employees may struggle to understand the distinction as well.
Consider Administrative Requirements
Voluntary benefits still require administration.
Depending on the program, this may involve employee eligibility, enrollment, payroll deductions, carrier coordination, employee communication, policy materials, and changes when employees join or leave the company.
Employers should understand those responsibilities before adding another product to the benefits package.
How Can Voluntary Benefits Fit Different Small-Business Workforces?
A broad small-business benefits strategy can still account for industry differences.
The type of work employees perform can influence what questions arise during benefits planning, but occupation alone should not determine which products an employee needs.
Roofing and Construction Businesses
Roofing and construction companies often employ people in physically active roles and may have teams working across multiple jobsites.
These employers may want to evaluate accident, disability, life, and other financial-protection benefits as separate components of their overall program.
Voluntary accident insurance should not be presented as a substitute for workers’ compensation or as a way to satisfy workplace insurance obligations. Its role depends on the terms of the individual policy.
Benefits information should also be accessible to workers who spend limited time in an office.
HVAC, Plumbing, and Electrical Companies
HVAC technicians, electricians, and plumbers frequently travel between customer locations and service calls.
For these employers, benefit accessibility and communication can be as important as product selection. Employees need to know what voluntary options are available, how enrollment works, where policy information is located, and whom to contact with questions.
A well-selected benefit has limited practical value if field employees do not understand that it exists.
Professional and Office-Based Businesses
Professional-services firms and office-based companies may have different workforce priorities.
Employees may have easier access to enrollment systems and benefits materials during the workday, but they still need clear explanations of how voluntary products differ from medical, disability, or employer-paid coverage.
Employers should evaluate the workforce rather than assuming office employees will automatically value a particular type of voluntary insurance.
Businesses With Both Field and Office Employees
Many growing small businesses have mixed workforces.
A company may employ technicians, customer-service staff, salespeople, supervisors, administrative workers, and managers. The benefits program needs to be understandable across these groups.
Employers should also administer eligibility according to applicable plan terms and legitimate employee classifications rather than making informal decisions based solely on perceived occupational risk.
How Should Employers Compare Voluntary Benefit Options?
Product comparisons should go beyond the name of the insurance. Two products described as accident insurance or critical illness coverage may operate differently. Employers should understand the policy before presenting it to employees.
Understand What Triggers a Benefit
Employers should know which events or circumstances may qualify for a benefit under the policy.
This is particularly important for accident, critical illness, and hospital indemnity products because employees may otherwise assume coverage applies more broadly than it actually does.
A short marketing description should not replace the policy definition.
Review Exclusions and Limitations
Every insurance product has terms that define how coverage works.
Employers should review exclusions, limitations, applicable waiting provisions, benefit restrictions, and other relevant policy language before summarizing a product for employees.
Employees should also know where they can find the formal policy information when they need more detail.
Understand Benefit Amounts and Structures
Voluntary products can differ in how benefits are calculated or paid.
Rather than relying on a generic explanation, employers should understand the specific structure of each option they offer.
This information can then be communicated without promising benefits that have not been confirmed.
Review Eligibility and Enrollment Requirements
Employers should confirm who may elect the coverage and when.
Eligibility rules, enrollment periods, dependent options, evidence requirements, or other procedures may differ by product.
These details should be included in the employer’s benefits administration process rather than addressed only when an employee raises a question.
Compare Employee Communication Requirements
Some products are easier for employees to understand than others.
If a voluntary benefit requires lengthy explanations before employees can distinguish it from another form of coverage, the employer may need a stronger communication plan.
Clear policy summaries, accessible documents, and a reliable benefits contact can support more informed enrollment.
How Should Small Businesses Explain Voluntary Benefits to Employees?
Communication affects whether employees understand what they are being offered.
A voluntary benefits presentation should identify the purpose of each product, explain who pays for it, and make formal policy information easy to find.
Clearly Label Voluntary Benefits
Employees should be able to distinguish between employer-paid benefits and coverage that requires an employee election or contribution.
Using the same general label for every benefit can make the program harder to understand.
The employer should clearly identify which options are voluntary and what action the employee must take if they want coverage.
Explain What Each Product Is Designed to Address
Plain language can make insurance products easier to understand.
Accident insurance should be explained as accident coverage subject to policy terms. Critical illness coverage should be tied to qualifying policy-defined conditions. Hospital indemnity should be explained according to its defined hospital-related benefits.
This is more accurate than using broad promises about financial security or healthcare expenses.
Explain How the Benefit Differs From Medical Coverage
Employees may see several health-related products and assume they work the same way.
Employers should make clear that supplemental products can operate differently from a medical plan. A hospital indemnity or critical illness benefit, for example, does not mean the policy functions as comprehensive health insurance. ProCare similarly separates ancillary products from its primary health-insurance offerings.
Make Formal Policy Information Accessible
Employees should know where to find the policy documents and plan-specific information associated with their elections.
A short enrollment guide can provide context, but exact benefits, exclusions, limitations, and eligibility rules should be verified through the applicable policy.
Establish a Resource for Detailed Questions
Managers should not be expected to interpret every insurance provision.
Employers can designate an appropriate carrier resource, plan administrator, benefits advisor, or internal contact for detailed questions.
This reduces the risk of employees receiving different answers depending on which supervisor they ask.
How Should Voluntary Benefits Be Managed During Enrollment?
Voluntary benefits should fit into the employer’s broader enrollment process rather than operate as a separate, confusing exercise.
Employees need enough context to understand how each option relates to the rest of their benefits.
Present Voluntary Benefits Alongside the Overall Benefits Package
Employees should first understand the core benefits available through the company.
Voluntary options can then be explained as additional choices with their own purposes and policy terms.
This makes the overall program easier to follow.
Give Employees Time to Review Their Elections
Optional insurance decisions should not be rushed.
Employees may want to review policy materials, discuss dependent coverage, or compare the benefit with coverage they already have.
Employers should communicate applicable deadlines clearly and allow employees to make their elections within the established process.
Confirm Elections and Waivers Where Applicable
Employers should maintain appropriate enrollment records according to the applicable program.
That may include recording employee elections, applicable waivers, or other required enrollment actions.
The goal is to know which employees elected coverage and whether administrative steps have been completed correctly.
Coordinate Applicable Payroll Deductions
When voluntary benefits involve employee payroll deductions, the benefits and payroll processes need to remain aligned.
Employee elections, deductions, coverage changes, and terminations should be handled according to the applicable procedures.
Clear ownership of these administrative tasks can reduce discrepancies later.
Keep Current Information Available After Enrollment
Employees may need policy information months after enrollment.
The employer should maintain a reliable source for current documents and contact information so employees can find help without searching through old emails or onboarding packets.
Review Voluntary Benefits as the Business and Workforce Change
A voluntary benefits program should be reviewed periodically.
Changes in workforce size, employee roles, core benefits, and participation can affect whether the existing options still fit the company.
Review Employee Participation
Participation patterns can provide context.
If very few employees elect a particular benefit, the employer may want to understand whether the product lacks relevance or whether employees simply do not understand it.
Participation alone should not determine the decision, but it can highlight questions worth reviewing.
Listen for Recurring Employee Questions
Repeated employee questions can reveal communication gaps.
If workers regularly confuse hospital indemnity with medical coverage or accident insurance with disability coverage, the issue may be how the products are being explained.
Better communication may solve the problem without changing the benefit itself.
Reassess Benefit Overlap
Changes to the core benefits package may affect voluntary options.
For example, adding or changing life, disability, dental, vision, or other coverage can create reasons to review how existing voluntary products fit with the new structure.
Review the Program as the Workforce Grows
A benefits program designed for a small team may need adjustment as the company adds employees, departments, locations, or new types of roles.
Periodic reviews help keep the package aligned with the workforce rather than preserving every benefit simply because it was offered in previous years.
How ProCare Consulting Helps Small Businesses Evaluate Voluntary Benefits
ProCare Consulting provides insurance and employee-benefits consulting services to businesses and specifically lists voluntary benefits among its small-group lines of coverage. Its employer offerings also include health plans, group life, AD&D, dental, vision, disability, and related benefits services.
For small employers, that broader perspective can help voluntary products fit into the overall benefits strategy instead of being evaluated in isolation.
Review the Existing Benefits Program
A useful review starts with what the business already offers.
Understanding existing medical, dental, vision, life, disability, and other coverage provides the context needed to evaluate whether additional voluntary options make sense.
Evaluate Appropriate Voluntary Benefit Options
Employers can review available voluntary products according to their workforce and benefits objectives.
The decision should include policy terms, employee eligibility, administrative requirements, communication needs, and how each option differs from current coverage.
Coordinate Voluntary and Core Benefits
A coordinated benefits strategy helps employees understand how different forms of coverage relate to one another.
ProCare’s small-group services cover multiple lines of employee benefits, including voluntary benefits alongside core and ancillary coverage.
This allows employers to consider the package as a whole rather than approaching each insurance product separately.
Support Employee Benefits Education and Enrollment
Employees need accurate information before making voluntary benefit elections.
Benefits guidance can help employers organize employee-facing information, explain available options more clearly, and establish resources for detailed policy questions.
Review Benefits as Business Needs Change
Employee benefits should evolve with the company.
As workforce size, roles, or business priorities change, employers can reassess whether existing voluntary benefits still serve a clear purpose and whether new options deserve consideration.
Frequently Asked Questions
What are voluntary employee benefits?
Voluntary employee benefits are additional benefits that eligible employees may be able to elect through an employer’s benefits program. The specific products, payment arrangements, eligibility requirements, and coverage terms depend on the employer and applicable policies.
Are voluntary benefits the same as supplemental insurance?
The terms are sometimes used together, but their meaning can depend on the context. Supplemental insurance generally refers to coverage designed to provide benefits in addition to other insurance, while “voluntary benefits” often describes benefits employees can elect through the workplace. Employers should use the terminology contained in their actual program and policy documents.
Are voluntary benefits always paid entirely by employees?
No. Funding arrangements can vary. Employers should clearly communicate whether a particular benefit is employer-paid, employee-paid, or subject to another contribution arrangement.
Can a small business offer voluntary benefits without offering every type of supplemental coverage?
Yes. Employers can evaluate individual benefit options according to the products available to them, their workforce, and the existing benefits package. There is no need to add every available voluntary product.
Is accident insurance the same as workers’ compensation?
No. Workers’ compensation and voluntary accident insurance are separate forms of coverage with different purposes, requirements, and terms. Employers should not present voluntary accident insurance as a replacement for workers’ compensation.
Does hospital indemnity insurance replace health insurance?
Hospital indemnity coverage is a separate type of insurance with policy-defined benefits. It should not be presented as a substitute for comprehensive medical insurance. ProCare lists hospital indemnity among its ancillary products separately from its small-group health plans.
What should employers consider before adding critical illness coverage?
Employers should review the policy’s covered conditions, exclusions, benefit structure, eligibility requirements, employee communication needs, and how the coverage fits with existing benefits.
Can employees choose which voluntary benefits they want?
When multiple voluntary options are available, eligible employees may generally have the opportunity to make elections according to the applicable program and policy requirements. Employers should communicate which options are available and when elections can be made.
How should a small business explain voluntary benefits during enrollment?
Employers should explain what each product is designed to address, who pays for it, how it differs from core medical or other benefits, which enrollment steps apply, and where employees can find the formal policy information.
How often should employers review voluntary benefit options?
Employers can review voluntary benefits periodically and when meaningful workforce or benefits changes occur. Changes in employee participation, core coverage, staffing, or business priorities can create reasons to reassess the existing program.
Conclusion
Voluntary employee benefits can give Florida small businesses additional ways to build a benefits package that reflects different employee needs. The strongest programs start with the coverage already in place and add voluntary products only when they serve a clear purpose.
Employers should understand how accident, critical illness, hospital indemnity, supplemental life, and other available products work before presenting them to employees. Clear distinctions between medical insurance, employer-paid benefits, voluntary coverage, disability insurance, and workers’ compensation can also reduce confusion during enrollment.
The benefits program should remain manageable for the business as well. Eligibility, enrollment, payroll coordination, employee communication, and ongoing administration should all be considered when evaluating a new option.
ProCare Consulting lists voluntary benefits as part of its small-group employee-benefits services, alongside health plans, life, AD&D, dental, vision, disability, and other employer solutions. For Florida small businesses, reviewing these options within the broader benefits strategy can help create a program that is easier for employees to understand and easier for the employer to manage.